The Main Reason Mortgage Rates Are So High
Today’s mortgage rates are top-of-mind for many homebuyers right now. As a result, if you’re thinking about buying for the first time or selling your current house to move into a home that better fits your needs, you may be asking yourself these two questions:
Here’s context you need to help answer those questions.
The 30-year fixed-rate mortgage is largely influenced by the supply and demand for mortgage-backed securities (MBS). According to Investopedia:
“Mortgage-backed securities (MBS) are investment products similar to bonds. Each MBS consists of a bundle of home loans and other real estate debt bought from the banks that issued them . . . The investor who buys a mortgage-backed security is essentially lending money to home buyers.”
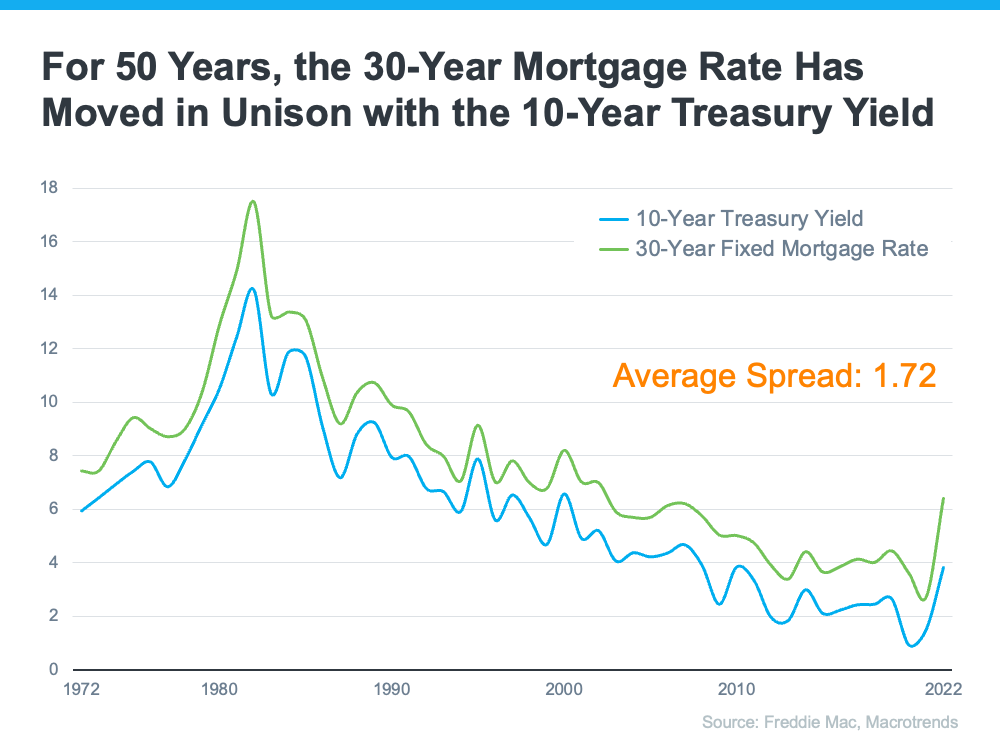
Demand for MBS helps determine the spread between the 10-Year Treasury Yield and the 30-year fixed mortgage rate. Historically, the average spread between the two is 1.72 (see chart below):
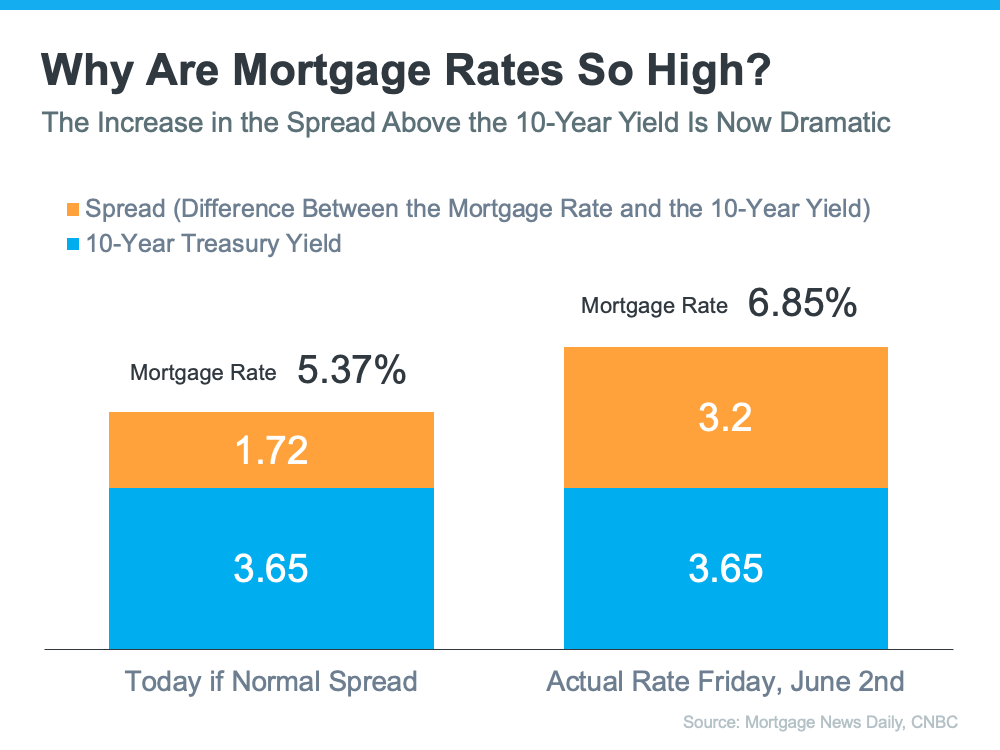
Last Friday morning, the mortgage rate was 6.85%. That means the spread was 3.2%, which is almost 1.5% over the norm. If the spread was at its historical average, mortgage rates would be 5.37% (3.65% 10-Year Treasury Yield + 1.72 spread).
This large spread is very unusual. As George Ratiu, Chief Economist at Keeping Current Matters (KCM), explains:
“The only times the spread approached or exceeded 300 basis points were during periods of high inflation or economic volatility, like those seen in the early 1980s or the Great Financial Crisis of 2008-09."
The graph below uses historical data to help illustrate this point by showing the few times the spread has increased to 300 basis points or more:
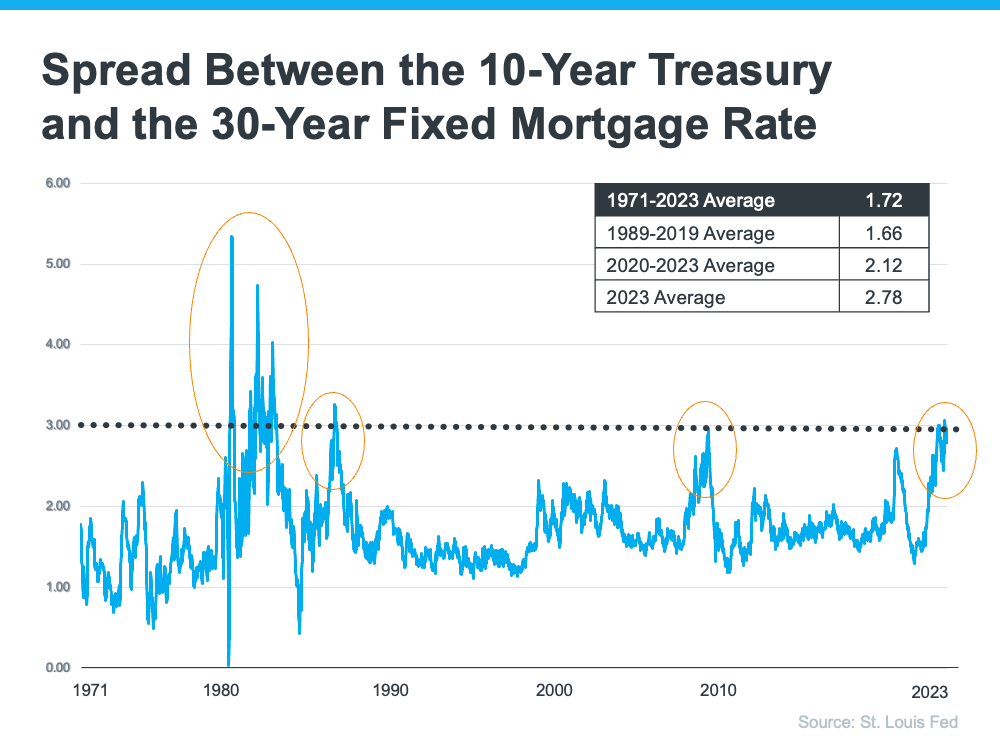
The graph shows how the spread has come down after each peak. The good news is, that means there’s room for mortgage rates to improve today.
So, what’s causing the larger spread and making mortgage rates so high today?
The demand for MBS is heavily influenced by the risks associated with investing in them. Today, that risk is impacted by broader market conditions like inflation and fear of a potential recession, the Fed’s interest rate hikes to try to bring down inflation, headlines that create unnecessarily negative narratives about home prices, and more.
Simply put: when there’s less risk, demand for MBS is high, so mortgage rates will be lower. On the other hand, if there’s more risk with MBS, demand for MBS will be low, and we’ll see higher mortgage rates as a result. Currently, demand for MBS is low, so mortgage rates are high.
Odeta Kushi, Deputy Chief Economist at First American, answers that question in a recent blog:
“It’s reasonable to assume that the spread and, therefore, mortgage rates will retreat in the second half of the year if the Fed takes its foot off the monetary tightening pedal and provides investors with more certainty. However, it’s unlikely that the spread will return to its historical average of 170 basis points, as some risks are here to stay.”
The spread will shrink when the fear investors feel is eased. That’ll mean we should see mortgage rates moderate as the year goes on. However, when it comes to forecasting mortgage rates, no one can know for sure exactly what will happen.
Stay up to date on the latest real estate trends.
Single-family home prices remain nearly 25% above year-ago levels at $2,050,000, even after easing modestly from June's peak.
The most striking story in the East Bay right now is how little is available for sale.
Single-family home prices have surged more than 26% year-over-year, marking the strongest annual gain we've seen this year.
Prices are rising across the board, with the condo market posting its strongest year-over-year gains in years.
Education
In many cases, the insurance proceeds received from a covered claim far exceeds the cost of the one-time premium paid for an owner’s policy of title insurance.
David's East Bay experience, creativity, and dedication to his clients made him a perfect fit for Elevation Real Estate
San Francisco's single-family home market continues to reach new heights, with the median sale price climbing 22.56% year-over-year to $2,200,000. This marks one of th… Read more
Prices are on the rise across the board, with single-family homes and condos both posting year-over-year gains for the first time in over a year.
Median sale prices continue their remarkable ascent, with single-family homes up more than 21% and condos up more than 18% year-over-year.
You’ve got questions and we can’t wait to answer them.