What You Actually Need To Know About the Number of Foreclosures in Today’s Housing Market
While you may have seen recent stories about the volume of foreclosures today, context is important. During the pandemic, many homeowners were able to pause their mortgage payments using the forbearance program. The goal was to help homeowners financially during the uncertainty created by the health crisis.
When the forbearance program began, many experts were concerned it would result in a wave of foreclosures coming to the market, as there was after the housing crash in 2008. Here’s a look at why the number of foreclosures we’re seeing today is nothing like the last time.
Today’s data shows that most homeowners are exiting their forbearance plan either fully caught up on payments or with a plan from the bank that restructured their loan in a way that allowed them to start making payments again. The graph below depicts those findings from the Mortgage Bankers Association (MBA):
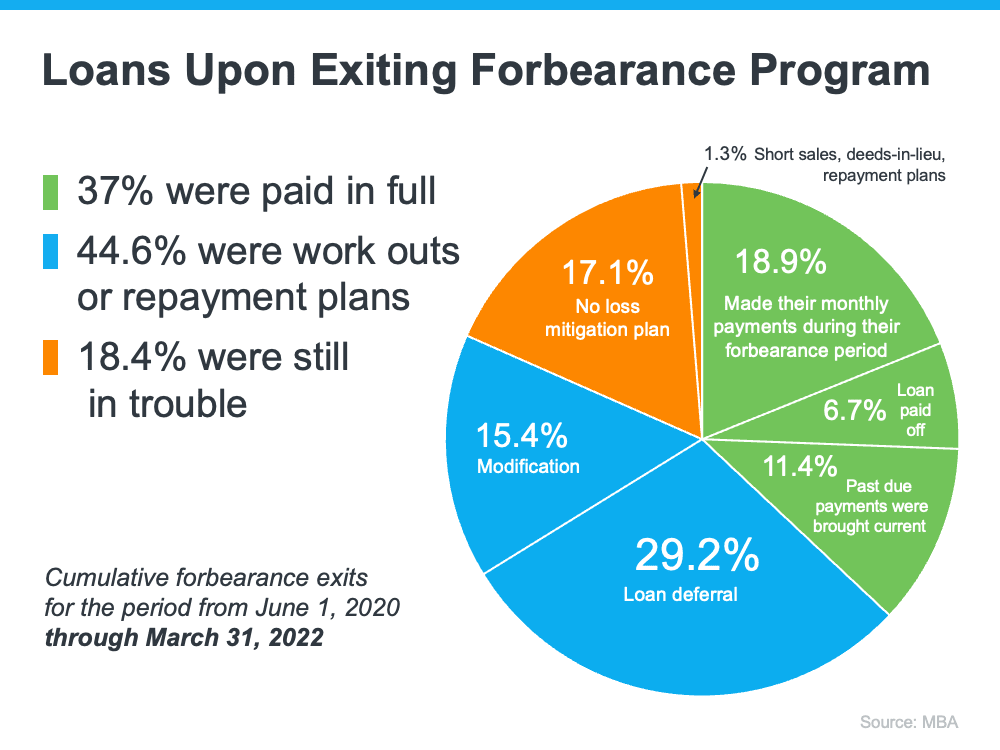
The same MBA report mentioned above estimates there are approximately 525,000 homeowners who remain in forbearance today. Thankfully, those people still have the chance to work out a suitable repayment plan with the servicing company that represents their lender.
For those who are exiting the forbearance program without a plan in place, many will have enough equity to sell their homes instead of facing foreclosures. Due to rapidly rising home prices over the last two years, the average homeowner has gained record amounts of equity in their home.
Marina Walsh, CMB, Vice President of Industry Analysis at MBA, says:
“Given the nation’s limited housing inventory and the variety of home retention and foreclosure alternatives on the table across various loan types, . . . Borrowers have more choices today to either stay in their homes or sell without resorting to a foreclosure.”
One of the seldom-reported benefits of the forbearance program was it gave homeowners facing difficulties an extra two years to get their finances in order and work out a plan with their lender. That helped prevent the foreclosures that normally would have come to the market had the new forbearance program not been available.
Even as people leave the forbearance program, there are still fewer foreclosures happening today than before the pandemic. That means, while there are more foreclosures now compared to last year (when foreclosures were paused), the number is still well below what the housing market has seen in a more typical year, like 2017-2019 (see graph below):

When the foreclosures in 2008 hit the market, they added to the oversupply of houses that were already for sale. It’s exactly the opposite today. The latest Existing Home Sales Report from the National Association of Realtors (NAR) reveals:
“Total housing inventory at the end of March totaled 950,000 units, up 11.8% from February and down 9.5% from one year ago (1.05 million). Unsold inventory sits at a 2.0-month supply at the present sales pace, up from 1.7 months in February and down from 2.1 months in March 2021.”
A balanced market would have approximately a six-month supply of inventory. At 2.0 months, today’s housing market is severely understocked. Even if one million homes enter the market, there still won’t be enough inventory to meet the current demand.
If you see headlines about the increasing number of foreclosures today, remember context is important. While it’s true the number of foreclosures is higher now than it was last year, foreclosures are still well below pre-pandemic years.
If you have questions, let’s connect to talk through the latest market conditions and what they mean for you.
Stay up to date on the latest real estate trends.
August delivered a familiar pattern for San Francisco's single-family market: strong annual growth paired with a seasonal retreat from the spring peak.
August delivered a steady, if unspectacular, close to the East Bay's summer selling season on the single-family side.
Single-family home prices remain nearly 25% above year-ago levels at $2,050,000, even after easing modestly from June's peak.
The most striking story in the East Bay right now is how little is available for sale.
Single-family home prices have surged more than 26% year-over-year, marking the strongest annual gain we've seen this year.
Prices are rising across the board, with the condo market posting its strongest year-over-year gains in years.
Education
In many cases, the insurance proceeds received from a covered claim far exceeds the cost of the one-time premium paid for an owner’s policy of title insurance.
David's East Bay experience, creativity, and dedication to his clients made him a perfect fit for Elevation Real Estate
San Francisco's single-family home market continues to reach new heights, with the median sale price climbing 22.56% year-over-year to $2,200,000. This marks one of th… Read more
You’ve got questions and we can’t wait to answer them.