The Down Payment Assistance You Didn’t Know About
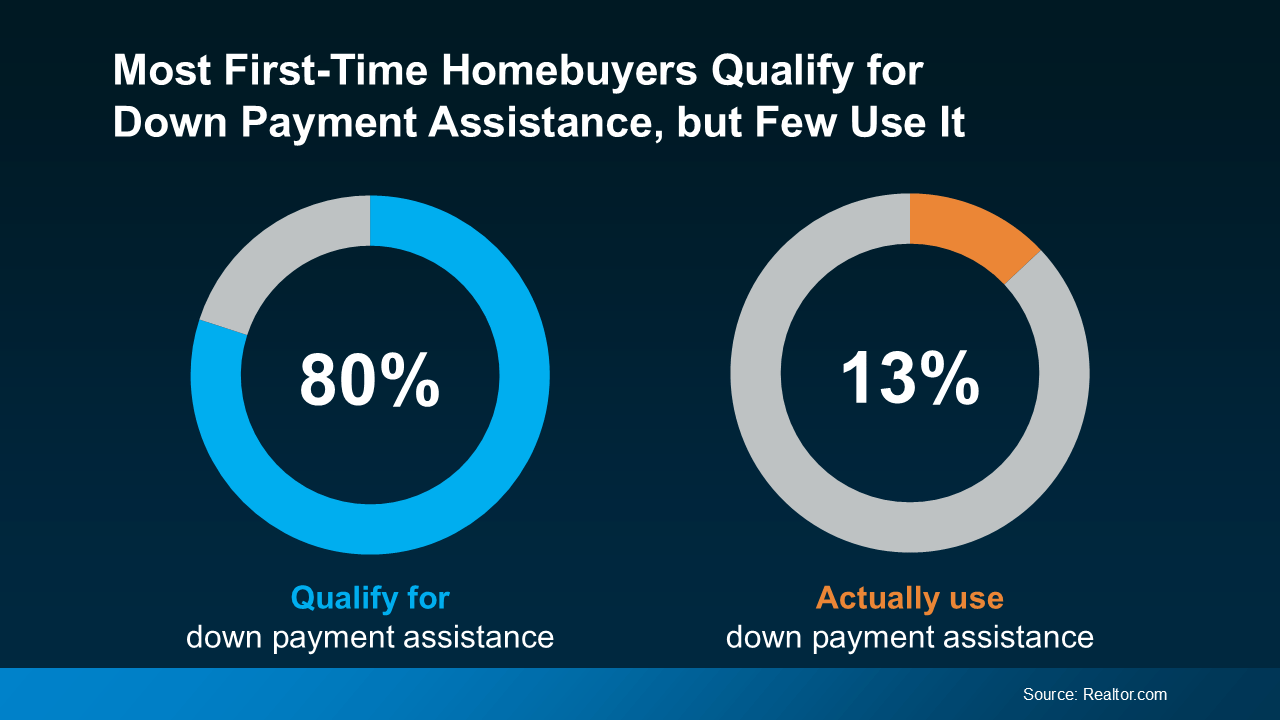
Believe it or not, almost 80% of first-time homebuyers qualify for down payment assistance, but only 13% actually use it. And if you’re hoping to buy a home, this is a mission-critical gap to close – fast (see graph below):
 Here’s what you need to know to make the most of your down payment in today’s housing market.
For first-time buyers, the name of the game with down payments is making sure you’re taking advantage of all the resources out there designed to help you. And a bunch of them can get you to your goal faster than you may have thought possible.
For example, there are loan options that require as little as 3% down, or even 0% for certain qualified borrowers, like Veterans. And let’s not forget down payment assistance, like grants and other opportunities, that help you cover the upfront cost of your down payment.
If you’re interested in exploring those options and what you may be able to use to your advantage, connect with a trusted lender. Because if you don't at least see what’s available, you could be leaving money on the table and missing your chance at buying a home. These resources can boost your down payment. And a higher down payment could help lower your eventual monthly mortgage payment, and even avoid or reduce your fees like private mortgage insurance.
There’s one more thing to address. News coverage has been talking about how the typical down payment is rising. A report from Redfin states:
“The typical down payment for U.S. homebuyers hit a record high of $67,500 in June, up 14.8% from $58,788 a year earlier . . . This was the 12th consecutive month the median down payment rose year over year.”
But don’t let those high dollars scare you. Just because the average down payment is rising doesn’t mean down payment requirements are going up. That’s a key piece of the puzzle to understand. It’s really just because people are choosing to put more down to try to offset higher mortgage rates, and current homeowners who are putting their equity to work are using that to increase their down payment on their next home. As HousingWire explains:
“. . . buyers are putting down a higher percentage of the purchase price to lower their monthly mortgage payment. And buyers also had more equity from their home sales, which gives them more cushion.”
Let’s break those two reasons down a bit:
1. A bigger down payment helps lower your monthly mortgage payment. Affordability has been a challenge for many buyers recently, which is why those who have the ability to make a bigger down payment are going to do so in an effort to lower their future housing costs.
2. Buyers who already own a home have a record amount of equity to leverage. Someone who bought a home a few years ago has gained a significant amount of value in their house, thanks to home price appreciation. These people can put down much more than the average first-time buyer who hasn’t owned a home yet.
What’s the best thing to do? Talk with a trusted lender about your options. They’ll help you figure out where you stand today and how to access the resources you may qualify for. Because help is out there, you just need to work with a pro to take advantage of it.
Stay up to date on the latest real estate trends.
August delivered a familiar pattern for San Francisco's single-family market: strong annual growth paired with a seasonal retreat from the spring peak.
August delivered a steady, if unspectacular, close to the East Bay's summer selling season on the single-family side.
Single-family home prices remain nearly 25% above year-ago levels at $2,050,000, even after easing modestly from June's peak.
The most striking story in the East Bay right now is how little is available for sale.
Single-family home prices have surged more than 26% year-over-year, marking the strongest annual gain we've seen this year.
Prices are rising across the board, with the condo market posting its strongest year-over-year gains in years.
Education
In many cases, the insurance proceeds received from a covered claim far exceeds the cost of the one-time premium paid for an owner’s policy of title insurance.
David's East Bay experience, creativity, and dedication to his clients made him a perfect fit for Elevation Real Estate
San Francisco's single-family home market continues to reach new heights, with the median sale price climbing 22.56% year-over-year to $2,200,000. This marks one of th… Read more
You’ve got questions and we can’t wait to answer them.